Chapter 2 - The Spreadsheet and the Hidden Debt
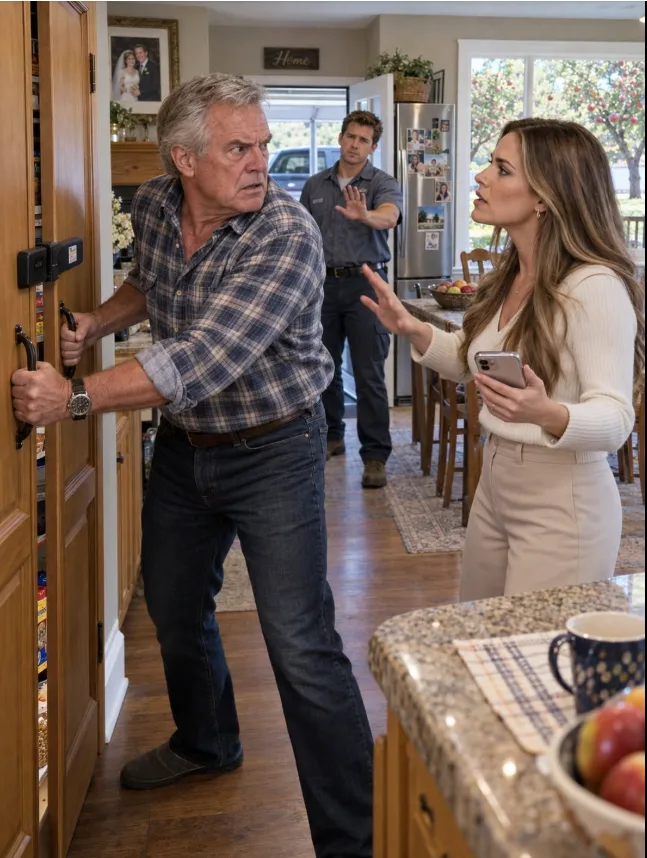
That night I lay awake beneath the pale blue wallpaper Louise had chosen, remembering comments I had dismissed as harmless chatter over the dinner table. Once, Brooke had stood outside my bedroom door, looking down the carpeted hallway with a calculating glint in her eye, and said, “Someday this could make a beautiful nursery.” Another time, while I was covered in grease and fixing the lawn mower, she had strolled into my sanctuary, looked around the garage, and remarked that it would be perfect for Miles’s home office once we cleared out the workbench. At the time, I had merely chuckled and swallowed my breath. Lying alone in the dark, listening to the hum of the old house settling, I didn’t find either comment funny anymore.
The next morning I woke around five-thirty. The house was cold and still. I brewed a fresh pot of coffee and walked into the kitchen, only to spot Brooke’s phone lying face-up on the dining table. I had no intention of snooping, but the screen suddenly illuminated with an incoming notification. Beneath the banner, I saw a row of open thumbnails from her recent camera roll.
My heart hammered against my ribs as I looked closer. There was my living room photographed from two professional angles, highlighting the hardwood floor and natural light. Another thumbnail showed the renovated kitchen, carefully angled to frame the center island. Then the backyard, focusing on the lot size rather than the garden. Finally, the garage. Every photograph was crisp, brightly lit, and leveled with precision. They weren't cozy family photos taken for a album. They were listing photographs meant to showcase a piece of real estate to prospective buyers.
I placed her phone back down, adjusting it to the exact angle I had found it.
Later that afternoon, while I was out back mowing the lawn, Miles walked across the yard with his hands shoved deep into his pockets. He stood near the edge of the patio, waiting for me to hit the end of a row. I killed the mower engine, and the sudden silence felt heavy.
“You okay about the lock thing, Dad?” he asked, shifting his weight.
“I’m fine,” I replied flatly.
Miles let out a small, audible breath of relief—a sound that cut deeper than an actual argument would have. He nodded, patted my shoulder awkwardly, and walked back inside to join Brooke.
Left alone under the shade of the apple trees, I leaned against the handle of the mower. Louise and I had bought this property thirty-two years ago for $110,000 when we were young, broke, and full of big dreams. I had patched the roof through three severe hail storms, sanded and refinished the oak floors by hand, upgraded the plumbing fixtures, poured the concrete patio with my brother, and made the final mortgage payment six years ago on the exact day I retired. I had never imagined I would stand in my own backyard, watching the afternoon shadow stretch across the grass, wondering whether someone else was quietly measuring my life's work for auction.
That evening, as I walked down the hall to fetch a blanket, I heard Brooke’s hushed voice drifting from the living room. She was on speakerphone, whispering sharply. “I’ll send Mom the rest of the staging photos later. Once the title situation is smoothed out, the appraisal will speak for itself.” I kept walking, keeping my footsteps soft against the runner rug.
Three days passed in an uneasy truce. On Thursday afternoon, I noticed another letter from Hartwell and Burn Realty sticking out from the shoe rack where Brooke kept her car keys. I didn't touch her mail, but I didn't need to. At lunchtime, while she was out at a bridal fitting and Miles was at his corporate desk, I pulled out my landline, dialed the agency's main branch, and explained that I was an owner inquiring about recent inquiries regarding my address.
The young receptionist on the line typed in my street address. I heard the clatter of her keyboard, followed by a sharp pause.
“Oh,” she said, her tone suddenly cautious. “It looks like a full property valuation and preliminary market report was requested for this address about two weeks ago.”
“By whom?” I asked, keeping my voice steady.
“I’m sorry, sir. Company policy prevents me from disclosing client details without a listing authorization.”
She didn’t have to give me a name. I had already seen Brooke’s full name printed neatly on the mailer. The estimated valuation on the property came out between $640,000 and $700,000 in the current hot suburban market.
There was no formal listing agreement, of course. Nobody could legally sell a single brick of my home without my signature. But as I sat at the quiet kitchen table, the silence felt deafening. Brooke didn’t hold a shred of legal authority over my life, yet she was already treating my home like an asset that was bound to land in her lap the moment she said “I do.”
The real breaking point came a week later. Miles rushed out the door for a last-minute client meeting, leaving his personal laptop open on the breakfast table. The screen glowed softly against the morning light. Displayed in full view was a complex financial spreadsheet titled: New House Budget — Miles & Brooke.
I wish I could say I walked away and respected his privacy. I didn’t. I leaned over the table and read every line.
Their projected target for buying a home was $500,000. There were columns for Miles’s accumulated savings, Brooke’s personal account, an estimated bank mortgage, and one line item near the bottom that made my blood run cold:
Dad Contribution: $125,000.
It didn't say Possible Gift. It didn't say Pending Dad’s Approval. It was listed as a concrete line item, factored directly into their bottom line as if it were cash already cleared in the bank. Beside the entry, in a light gray shaded cell, was a small bulleted comment:
Note: If down payment gap increases, consider leverage options or short-term listing on Dad’s property post-wedding.
I read those words three times until the text blurred before my eyes.
The alarming part wasn't merely that Brooke was feeling entitled to my retirement funds. The terrifying part was that I had never shared that specific dollar amount with her. I had once told Miles over a quiet beer on the porch that I had set aside some savings to help them build a foundation after the wedding. But I had never uttered the figure $125,000 out loud. That number existed in only one place: a locked leather notebook inside the middle drawer of my desk in the home office.
Somehow, Brooke had found it. Whether she had quietly searched my private files, or whether Miles had let it slip during a late-night conversation, didn't matter anymore. What mattered was how she interpreted my generosity. She hadn't seen a loving parent offering a helping hand; she had identified a passive asset waiting to be exploited.
That night, after everyone was asleep, I went into my office and pulled out my financial folders. The deed was clean, held solely under my name: Arthur Edward Miller. My retirement distribution accounts were locked. My late wife’s life insurance policy payout remained untouched in a high-yield account.
I leaned back in my leather chair, remembering the crisp autumn afternoon four years ago when I held Louise’s hand in her hospice room. Her voice had been barely a whisper. “Artie,” she had said, looking into my eyes, “don't let anyone take advantage of what we spent thirty years building. Make sure Miles earns his path, or he’ll never learn how to stand on his own.”
I had promised her I would guard our family. At the time, I thought she was just being an anxious mother worrying about a young boy's future. Sitting in the quiet darkness of my office, I realized I had mistaken enabling my son for protecting him.
Before going to bed, I logged into my bank dashboard to check my monthly statements. Scrolling through my primary credit card activity, I noticed an unexpected pattern. Years ago, when Miles went off to college, I had added him as an authorized user on my Visa account for genuine emergencies. I had completely forgotten the card was still active.
Over the last three months, that card had seen heavy, consistent use.
Weekly trips to the upscale grocery store downtown. $180 here. $240 there. Bulk purchases at high-end specialty markets. Hundreds upon hundreds of dollars spent on gourmet items, household supplies, and daily provisions.
May you like
I stared at the statements, feeling an eerie chill run through me. Brooke had been using my authorized credit card to purchase all the food, groceries, and household goods brought into the house.
And then she had put a $29 electronic lock on the pantry doors to keep me out of the very food I was paying for.