Chapter 3 - The Midnight Ledger
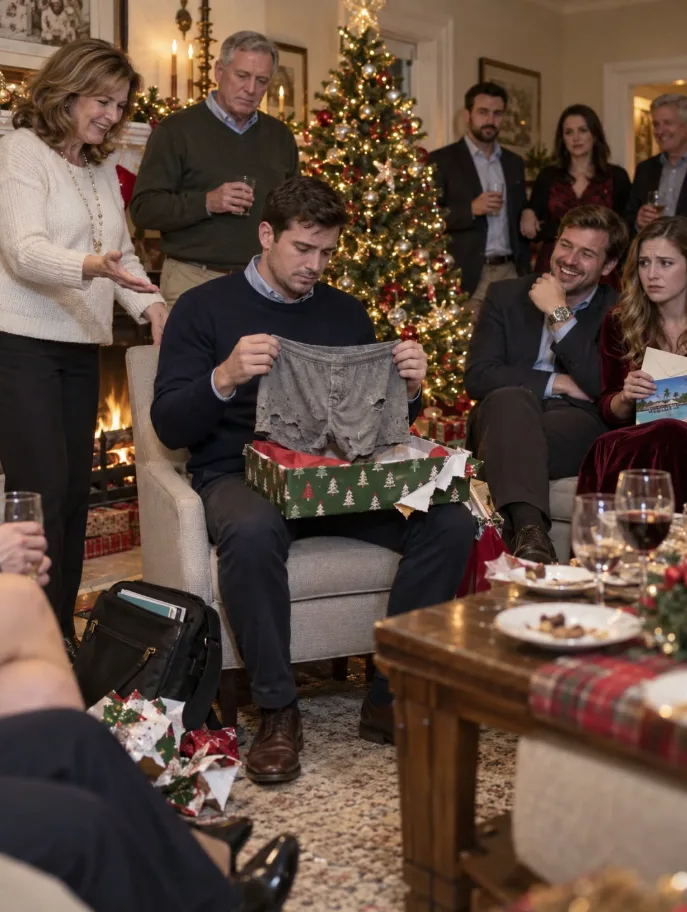
The drive back to my two-bedroom rental apartment in Midlothian took twenty-five minutes. My hands stayed clamped to the steering wheel, my knuckles pale under the dashboard’s faint amber glow.
I didn't turn on the radio. I didn't want Christmas carols. I wanted the cold, humming hum of my tires against the asphalt.
When I walked into my apartment, the quiet felt different. Usually, I loved this space. It wasn't large, but it was mine. Bookshelves lined the living room, filled with historical biographies, student papers I’d saved over the years, and framed photos from hiking trips in Shenandoah.
I hung my coat by the door, walked straight to my small oak desk in the corner of the dining area, and booted up my laptop.
My phone on the kitchen counter began to vibrate violently against the granite.
*Incoming Call: Tyler.*
I ignored it. Three seconds later: *Incoming Call: Amanda.*
I switched the phone to silent and set it face down.
I opened my email and found the folder labeled *Refinance - 442 Elmwood*. The senior lending officer at Richmond Federal Credit Union, a sharp, no-nonsense woman named Marcus Vance, had emailed me the complete disclosure packet six days ago after I submitted my pay stubs and tax returns.
At the time, I had skimmed the closing documents through a lens of filial duty. Dad was in trouble; I was the responsible son stepping up to help. I hadn't scrutinized every single line item of the liabilities schedule.
Now, with the image of Tyler’s gleaming watch and Amanda’s glossy travel voucher burned into my retina, I opened the PDF attachment labeled *Schedule B - Debt Payoff Authorization*.
I zoomed in to four hundred percent.
Line item twelve: *Chase Sapphire Preferred - Balance: $6,450.00.*
Line item thirteen: *Delta SkyMiles American Express - Balance: $4,820.00.*
My breath caught in my chest.
Beside each account was an origination date.
The Chase Sapphire card had been opened on November 3. The Delta American Express had been opened on November 14.
Both accounts were less than seven weeks old.
I stared at the numbers until the screen blurred.
My father had sat in my living room on December 12, sobbing into his coffee mug, telling me that medical bills from his arrhythmia ablation and emergency room visits were choking them to death. And while he was preparing that desperate plea, my mother was out running up eleven thousand dollars on high-interest credit cards to buy an all-inclusive Caribbean vacation and a luxury timepiece.
They hadn't just bought those gifts out of foolish pride. They had bought them *knowing* that I was going to consolidate their debt on December 28.
They had used my credit score as an open bar tab for Christmas shopping.
The sheer arrogance of it made my stomach churn. They had stood in that kitchen, watched me open a box containing discarded rags, and laughed at my modest teacher’s wage while relying on that very same teacher’s financial reputation to pay off the extravagant gifts they handed to their favorite children.
A soft ping came from my computer. An email notification popped up in the corner of the screen.
It was from Marcus Vance at the credit union. The timestamp read 8:45 PM on Christmas Eve.
*Dear Daniel,*
*I apologize for reaching out outside normal business hours on a holiday, but I received an automated alert from our underwriting system regarding your parents’ file. An additional hard inquiry appeared on Arthur and Eleanor’s credit report this afternoon from a local retail jeweler’s financing arm (Synchrony Bank), totaling $3,200.*
*Because this new debt was incurred prior to closing, our underwriting guidelines require us to recalculate the debt-to-income ratio before Tuesday morning. As the primary guarantor, this will increase your total liability obligations under the secondary mortgage terms.*
*Please call me first thing Monday morning to discuss how you wish to proceed.*
*Best,*
*Marcus Vance*
*Senior Mortgage Underwriter*
I leaned back in my chair, staring at the ceiling.
Tyler’s watch hadn't just cost six thousand dollars. The card hadn't covered the whole balance, so my mother had opened *another* retail store credit line right at the counter to bridge the difference. Today. On Christmas Eve. Just hours before they handed me Dad’s torn underwear.
They weren't drowning in an inescapable tragedy. They were addicted to the theater of wealth, and they had chosen me to pay for the tickets.
I closed the laptop screen.
For seven years, I had quietly absorbed their jabs. I had smiled through Thanksgiving dinners when Tyler bragged about his quarterly bonuses. I had nodded politely when Amanda explained that public schools were “glorified daycare centers” compared to the private academies she planned for her future children. I had kept my head down, lived beneath my means, saved fifteen percent of every single paycheck, and built an impeccable life based on discipline and honest work.
They thought I was weak because I was kind. They thought I was broke because I drove a ten-year-old car.
I reached for my phone. It had eight missed calls and six text messages.
One from Tyler: *Dan, call me right now. Mom is having an anxiety attack and Dad’s blood pressure is spiking. You need to fix this.*
One from Amanda: *I can’t believe you would ruin Christmas like this. You’re so bitter about our careers it’s sickening.*
And one from Dad, sent just four minutes ago: *Daniel, I am so sorry. You don't know the whole story. Please come to the house tomorrow morning. Just you and me.*
I typed a single response and sent it to all three of them in a group thread:
*“I’ve seen the underwriting disclosures from Marcus Vance. I know about the Chase card. I know about the Delta card. And I know about the jewelry store financing opened this afternoon. Nobody calls me. We will all meet at the Richmond Federal branch on Broad Street at 9:00 AM on Tuesday. If Mom isn't there, don't bother showing up.”*
May you like
Then I shut my phone completely off, walked into my bedroom, and slept better than I had in months.
***