Chapter 2 - The Sunday Trap & The Audit
The silence that followed my ultimatum had lasted exactly twelve seconds before Chase grabbed Harper by the elbow, whispering frantically about avoiding a scene. They had hauled three boxes down the stairs, slammed their Lexus doors, and peeled out of my gravel drive, leaving my front gate swinging wide on its hinges.
Three days later, I was sitting at my parents' dining room table.
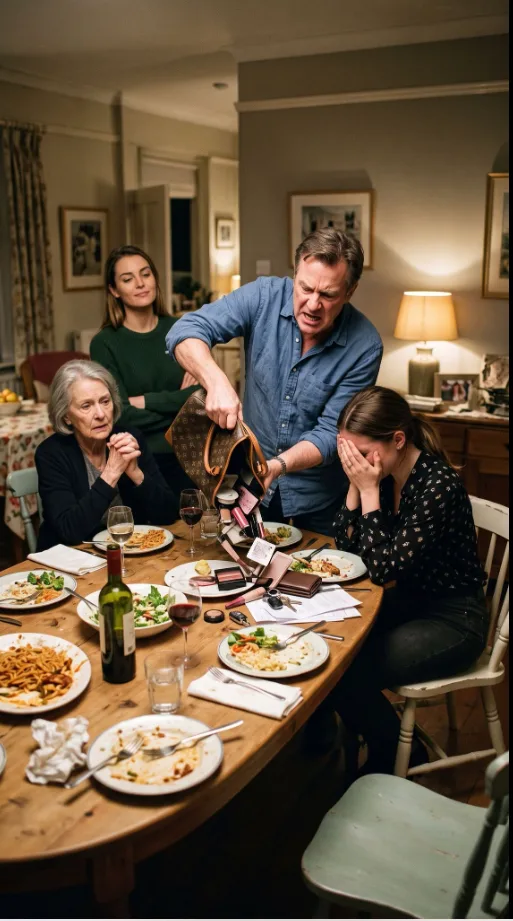
The dining room smelled of rosemary and slow-cooked braised short ribs—my favorite meal, the one my mother only made when she was preparing an ambush.
My mother, Eleanor, bustled in from the kitchen carrying a porcelain gravy boat. She wore her pearls and her practiced matriarchal warmth. My father, Thomas, sat at the head of the table, cutting his meat with mechanical precision, his eyes glued firmly to his plate. He hadn’t looked directly at me since I walked through the front door.
Opposite me sat Harper and Chase. Harper had spent the last seventy-two hours playing the wounded martyr on family group chats, claiming I had caused her “acute prenatal distress.” Chase sat with his shoulders squared, wearing his tailored blazer, radiating the unearned arrogance of a man whose debts were always paid by someone else.
Halfway through the meal, Chase cleared his throat, setting his silverware down with a calculated chime against the china.
“Our downtown loft has simply gotten too small,” Chase began, looking smoothly between my parents and me. “With the new remote consulting contracts I'm taking on, plus the baby arriving in four months, the footprint isn't tenable. The noise, the parking… it’s not an environment for a newborn.”
My mother immediately chimed in, clasping her hands over her napkin. “Which brings us to Naomi’s property. We really need to look at this rationally, Naomi. You’re gone half the year. An empty four-bedroom house sitting out there on the marsh while your sister struggles in a cramped two-bedroom rental is just poor stewardship. It’s excessive.”
Harper set her fork down and looked across the table at me, her chin tilted up. “We need your house for the baby, Naomi.”
Not: *Can we rent your guest wing?*
Not: *Could you help us find a place?*
*We need your house.*
“And where do you propose I live when I’m off-rotation?” I asked, keeping my voice mild as I sliced a carrot.
“Well, you could take our apartment lease downtown,” Chase offered magnanimously, as if handing me a winning lottery ticket. “Or take the in-law suite over your garage once we convert it. We'd handle the utilities while you're at sea.”
“Fascinating,” I replied. “Because generally, when people propose taking over a half-million-dollar deed, they don’t start by breaking in and painting the walls before asking.”
“Naomi, stop being dramatic!” my mother snapped, dropping the sweet act instantly. “Nobody broke in. I gave them your spare key. You have an obligation to this family!”
“I have an obligation to my mortgage lender,” I countered, standing up from the table. “And my answer is absolute, non-negotiable no.”
The dinner ended in shouted recriminations, my mother calling me heartless while Harper theatrically clutched her stomach. But as I drove home through the humid evening, something bothered me deep in the pit of my gut.
Chase hadn’t looked angry at the table. He had looked *panicked*.
The following morning at 0500, I sat in my home office with a pot of black coffee and treated the situation not as a petty domestic squabble, but as an operational threat assessment.
I pulled up the county clerk’s portal, running my parcel number through the public registry. Then I pulled my full credit bureau profiles, business entity filings with the Secretary of State, and Chase’s commercial records for *Sterling Auto Consulting LLC*.
What I found made the blood drain from my face.
Three weeks ago, while I was patrolling hundred-fathom curves in the Gulf, a commercial lender named Blue Ridge Capital had run two hard credit inquiries tied to my residential parcel. Attached to the pending file was an application for a $350,000 small-business loan under Chase’s LLC.
On the application, Chase had listed my physical address as his primary residence and business headquarters for the past three years.
Even worse: the application listed my property as an unencumbered owner-occupied asset backing the loan guaranty.
My fingers flew across the keyboard. Chase’s business was hemorrhaging cash. Liens from former vehicle-auction partners, two default judgments from local suppliers, and an eviction notice pending on their luxury downtown loft for three months of unpaid rent. The loan from Blue Ridge was his Hail Mary—and the approval was conditionally tied to a physical site verification scheduled for that very week.
Then came the final nail.
I checked my USPS delivery digest and cross-referenced it with registered mail logs. Three certified letters from Blue Ridge Capital had been delivered to my mailbox while I was offshore.
The digital signature on the delivery scan wasn't mine.
It was my mother’s unmistakable looping cursive: *Eleanor Vance.*
May you like
She hadn’t just handed Chase my keys. She had intercepted my certified mail, signed for financial documentation under my name, and actively facilitated an attempt to anchor Chase’s failing fraudulent business to my front door.
***