Chapter 3 - The Architecture of an Illusion
To understand how my family arrived at the conclusion that they could steal a four-hundred-thousand-dollar property from beneath my feet, you have to understand the specific brand of mythology Teresa Miller had cultivated for thirty years.
In our family, there were two distinct castes: the decorative and the functional.
Vanessa was the decorative. From the moment she won third runner-up in a suburban junior pageant at age seven, Teresa had treated her like an imported porcelain vase. She was given piano lessons she never practiced, private tennis coaches she fired after two sessions, and an unshakeable conviction that her mere physical presence in a room was a generous contribution to society.
I was the functional.
When the basement flooded in our old house in Berwyn, I was the one who hauled the wet boxes up the concrete stairs while Vanessa had her nails painted for a high school dance. When Arthur lost his dispatch supervisor job at the rail yard in 2018, I was the one who balanced their debt-consolidation spreadsheet between my college finals, discovering that my mother had opened four separate retail credit cards in my name to buy Vanessa’s sorority wardrobe.
I paid them off. I didn't call the police. I didn't file an identity theft report. I told myself that family was an endurance sport, and that if I just absorbed the friction quietly, we would eventually reach a smooth stretch of road.
That delusion died in 2021.
Five years ago, Arthur’s health began to fail. His knees were shot from thirty years on concrete loading docks, and the steep stairs of their suburban two-story house were becoming an insurmountable daily obstacle. Around the same time, Vanessa announced that she had been hired as a "senior client relations associate" at a boutique PR firm in River North.
She needed to live like a high-earning urban professional. She couldn't possibly commute from the blue-collar sprawl of Berwyn; she needed an address with brick walls, exposed ductwork, and an espresso bar within walking distance.
She found a three-bedroom vintage condo in an eight-unit brick building on Belden Avenue in Lincoln Park. The building was solid, constructed in the 1920s with thick masonry, hardwood floors, and wide arched doorways. It had a private elevator that opened directly into the foyer—perfect for Arthur’s failing joints.
The purchase price was $385,000.
Vanessa qualified for exactly nothing. Her credit score was a smoking crater of unpaid Zara charge accounts and delinquent auto-lease payments. Arthur and Teresa had an equity payout of barely sixty thousand dollars from the sale of the Berwyn house, after clearing their secondary liens.
Teresa had called me into the kitchen of their temporary rental, her eyes red, her hands trembling over a cup of instant coffee.
“Dani, please,” she had wept, gripping my forearm until her rings dug into my skin. “Your sister is finally building a real career. She can’t take clients to a rental in Cicero. If we buy this condo together, your father can have his elevator, Vanessa can have her professional image, and we will all share the equity. You have the cash from your pharmaceutical contracts. You're the only one who can save this family.”
I had looked at my bank account. I had twenty-eight years old, married to Mark, earning a comfortable six-figure income as a senior regulatory copy editor, with no debt and a substantial down payment fund.
I didn't give them a gift. I wasn't that stupid.
I went to a real estate attorney on North LaSalle Street named David Sterling—a man who specialized in high-conflict commercial property litigation and estate asset protection.
“If you want to house your parents, Dani, that’s your choice,” David had told me, tapping a gold pen against his desk. “But you do not co-sign a residential mortgage with your sister. You do not put your name on a joint tenancy with people who have three active collections accounts. If you put up the capital, you hold the paper.”
We executed a private structured acquisition.
My parents provided their $60,000 cash from Berwyn. I provided $120,000 in liquid capital from my private investment reserves to cover the down payment, the closing costs, and a mandatory structural repair escrow demanded by the building association.
To satisfy the secondary lender without triggering an institutional gift-tax audit, the primary mortgage was drafted in Arthur’s name, backed by a private, unrecorded Master Warranty Deed executed simultaneously by Arthur and Teresa.
Under the terms of that deed, Arthur and Teresa held a revocable life-estate occupancy right, contingent upon two non-negotiable clauses:
Clause 4, Section B: The occupants shall be responsible for routine interior maintenance and utility obligations. Any structural encumbrance, refinancing, or secondary lien placed upon the property without the express, notarized written consent of Danielle Miller shall trigger an immediate, automatic forfeiture of the life estate, reverting full fee-simple title and immediate right of possession exclusively to Danielle Miller.
Clause 7, Section A: In the event that the primary mortgage payments or property tax escrows are subsidized by Danielle Miller for a continuous period exceeding twenty-four (24) consecutive months, all equitable interest previously claimed by the occupants shall be deemed liquidated and transferred to the primary investor.
They had signed it. Arthur had signed it while watching a football game; Teresa had signed it while complaining about the price of the notary fee.
They signed it because in 2021, Vanessa had promised that within six months, her firm would make her a junior partner, and she would take over the entire mortgage payment of $1,850 a month.
Vanessa made exactly two payments.
In March of 2021, she bought a leased Audi. In June, she decided she needed to move into her own "luxury sanctuary" in Evanston—a one-bedroom condo with a view of the water that carried a monthly mortgage of $1,200.
For five years—sixty consecutive months—the mortgage payment on the Lincoln Park condo had been paid directly from my private business checking account via automated clearing house transfers.
Sixty months at $1,850: that was $111,000 in direct principal and interest.
And for those same five years, Vanessa had called me on the twenty-seventh of every single month, crying about her commission checks being delayed, begging me to transfer $1,200 to her mortgage servicer in Evanston so her condo wouldn't fall into default.
“Just this month, Dani,” she would whisper over the phone, her voice thick with fake tears. “If Mom finds out my account is negative, it will break her heart. You know how her blood pressure is. I’ll pay you back when my quarterly bonus clears.”
She never paid back twelve cents.
I had poured $72,000 into her Evanston mortgage. I had poured $111,000 into the Lincoln Park building. Combined with my initial $120,000 down payment, I had invested $303,000 of my own hard-earned money into their comfortable suburban existence.
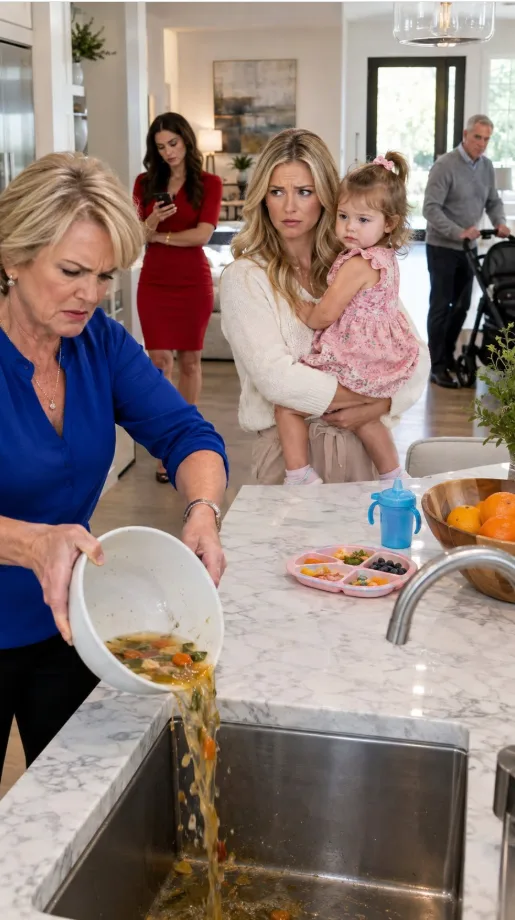
And tonight, Teresa had ripped a sixty-cent bowl of chicken soup out of my daughter’s hands, dumped it down a greasy drain, and my father had pushed her stroller into an arctic blizzard to ensure they could forge my signature on an equity loan on Monday morning.
May you like
I looked at the digital clock on the desk: 12:15 AM.
I picked up my phone, dialed David Sterling’s private after-hours line, and waited for the tone.